What should a European buyer put in the contract?
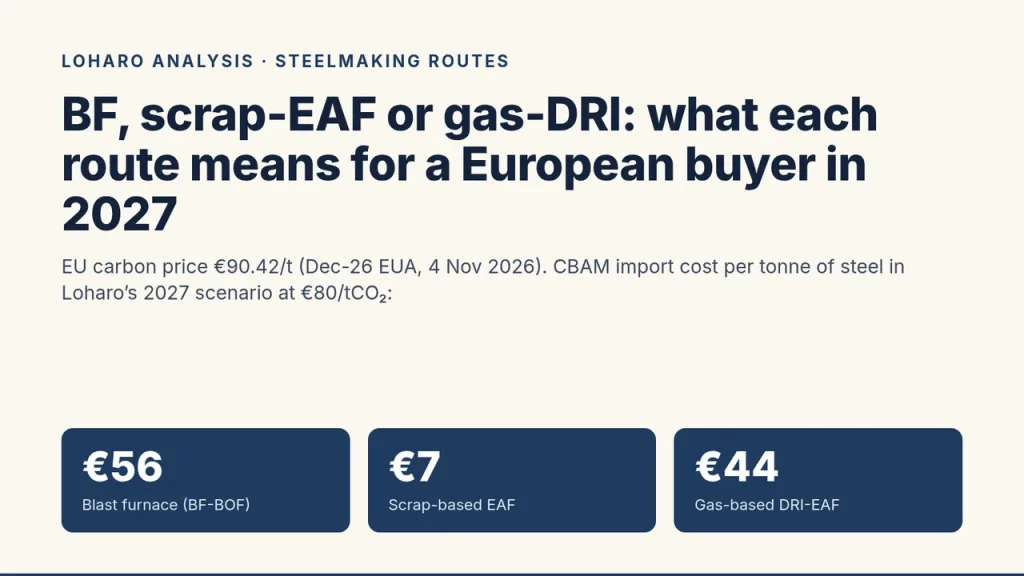
For a European buyer negotiating 2027 steel supply, a furnace label is not a delivery or carbon guarantee. Put the grade, delivery milestone, measured emissions and substitute-supply rights in the contract. The carbon side now matters more: the benchmark EU carbon allowance was €90.16/t on 5 November 2026 (Dec-26 contract; €89.19 settlement on 30 October), so we show CBAM import costs at €60, €80 and €100/tCO₂.
Reach steel buyers and importers worldwide
Put your brand in front of the people who buy and trade steel.
Advertise with LoharoWe no longer quote dollar cost bands. Published route costs still rest on pre-2022 inputs, so we give relative cost only: Columbia’s 2024 review puts BF-BOF lowest on global average, scrap-EAF close behind and gas-DRI above both, with wide regional swings. The IEA’s 2025 review puts early fully hydrogen-based plants 50–140% above BF-BOF. Gas-DRI and hydrogen-DRI are not the same offer.
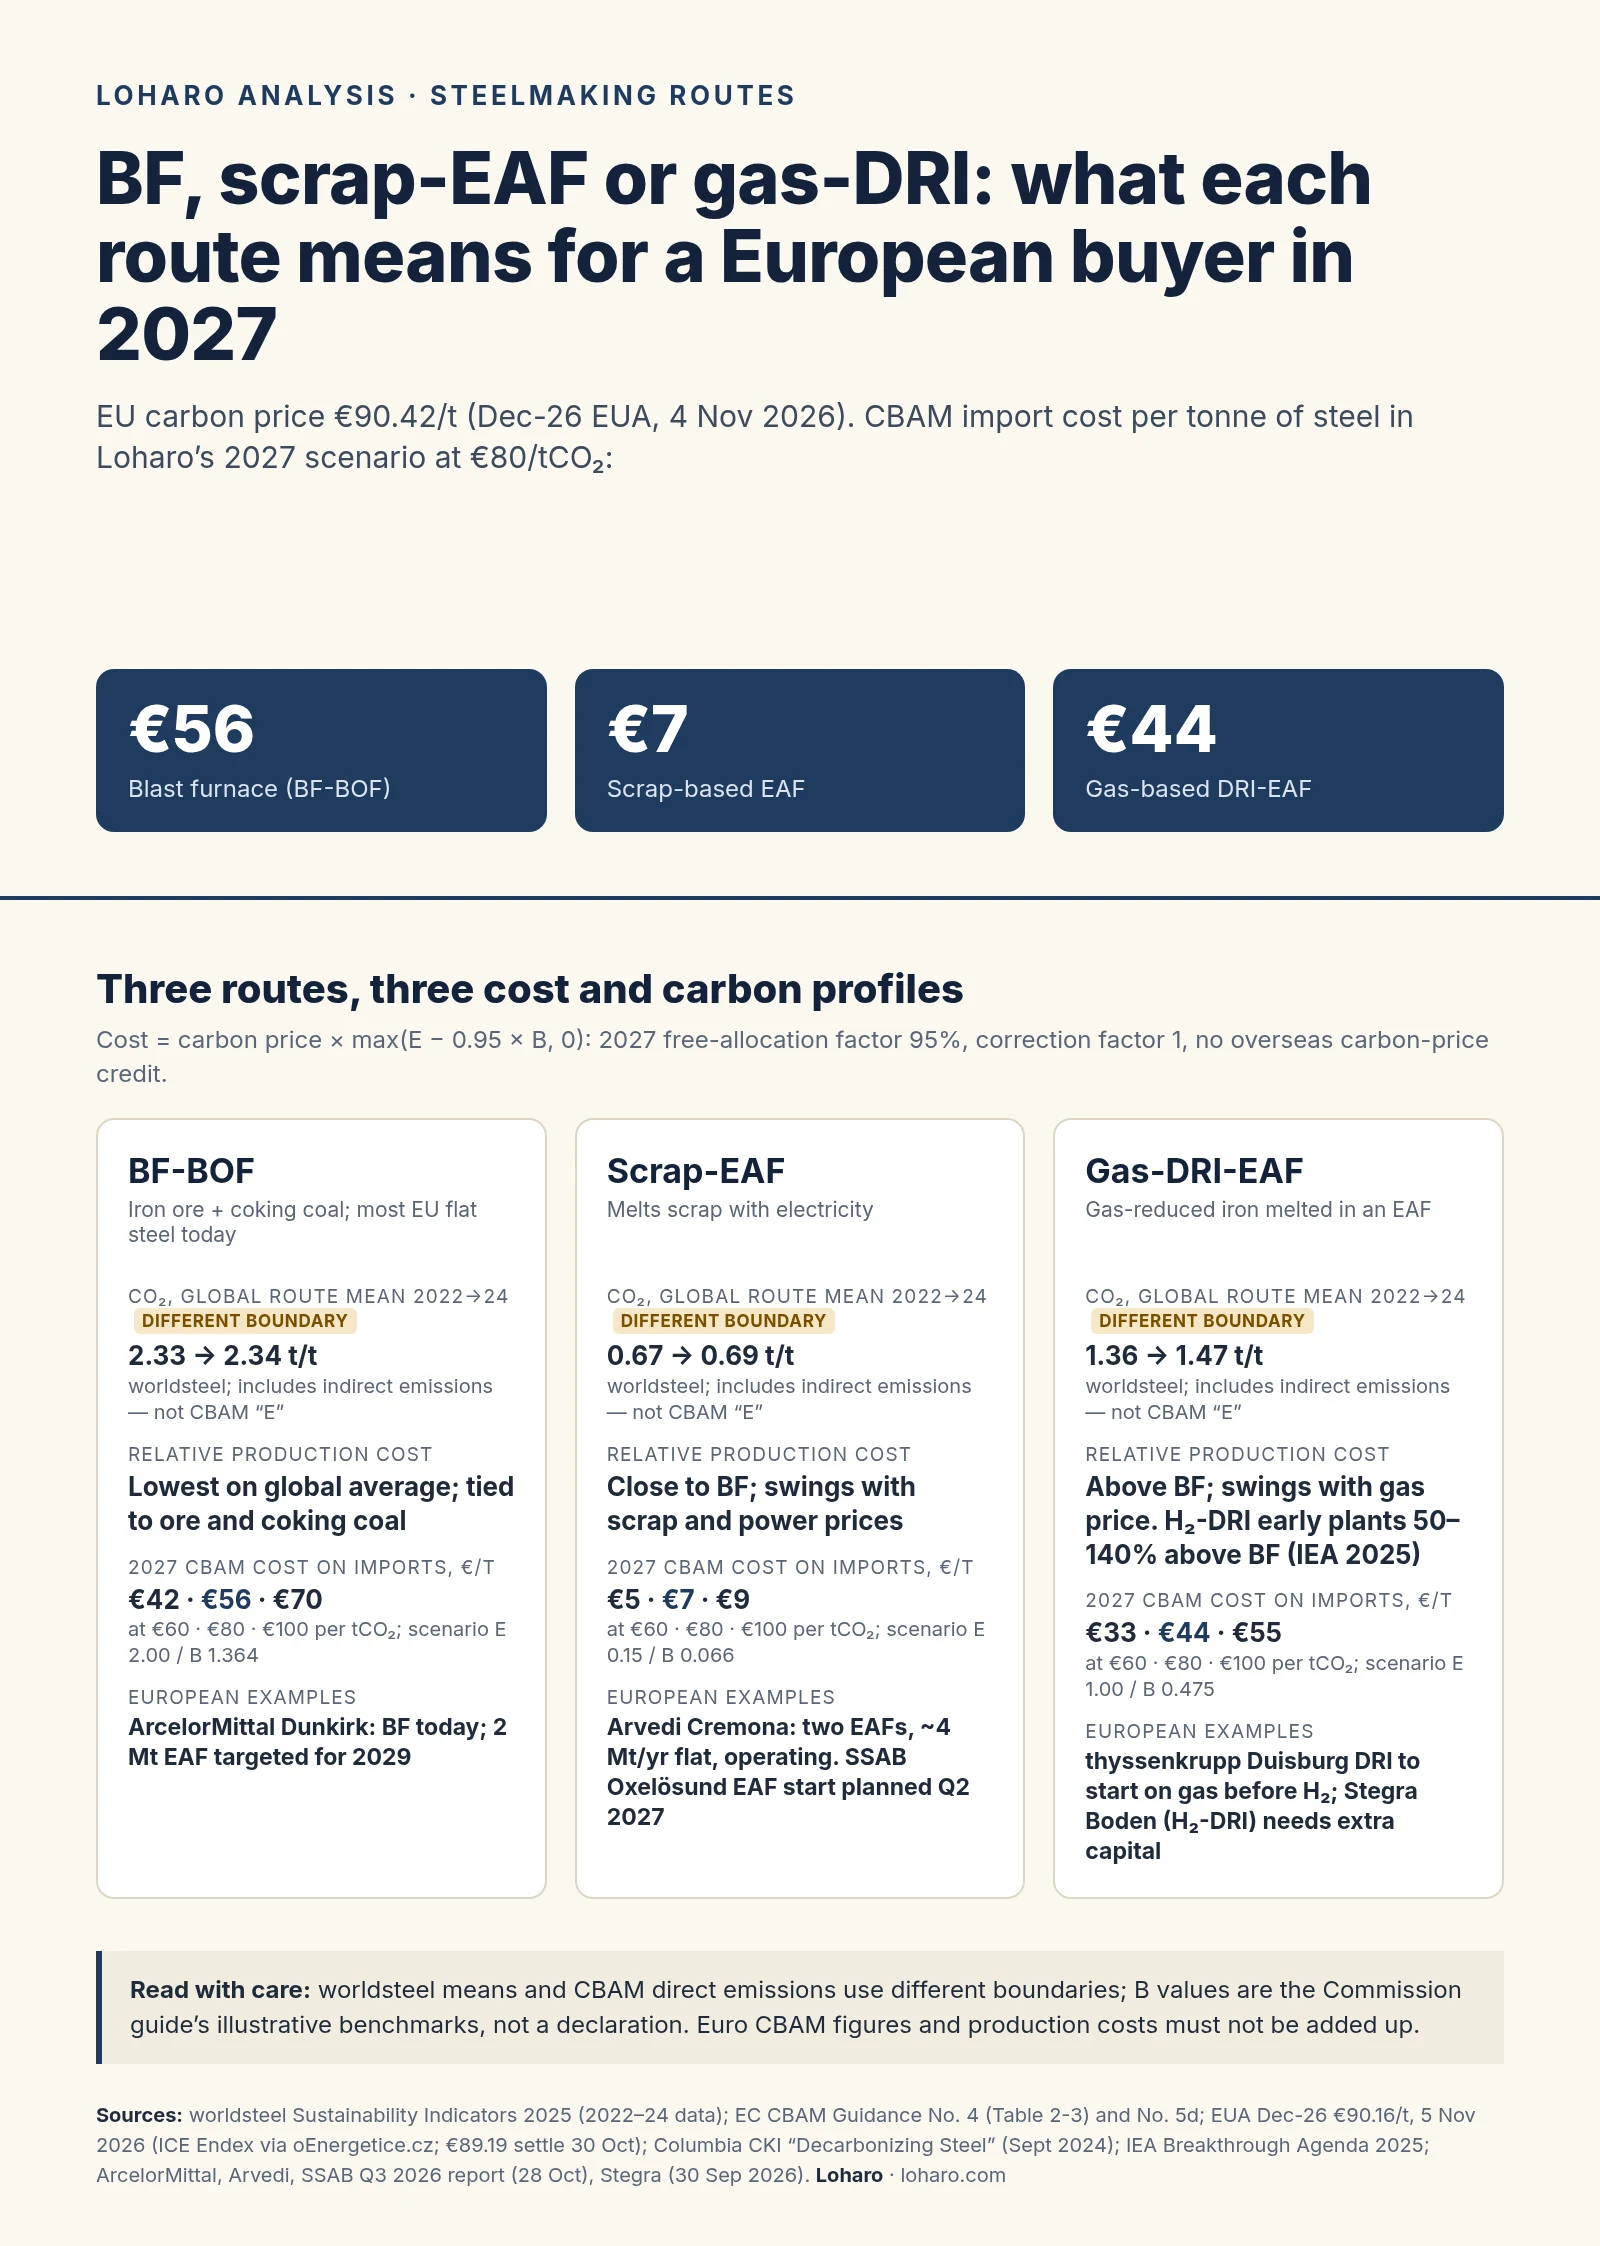
| Route | 2022 → 2023 → 2024 CO₂, t/t (worldsteel) | Scenario E / B, t/t | 2027 CBAM, €/t at €60 / €80 / €100 |
|---|---|---|---|
| BF–BOF | 2.33 → 2.33 → 2.34 | 2.00 / 1.364 | 42.25 / 56.34 / 70.42 |
| Scrap–EAF | 0.67 → 0.69 → 0.69 | 0.15 / 0.066 | 5.24 / 6.98 / 8.73 |
| Gas-DRI–EAF | 1.36 → 1.43 → 1.47 | 1.00 / 0.475 | 32.93 / 43.90 / 54.88 |
Keep the boundaries separate
The history uses worldsteel’s original CO₂ series, not its expanded greenhouse-gas indicator. These global annual means include electricity and other boundaries beyond CBAM direct emissions; the DRI series also mixes gas and coal-based reduction. They are neither mill-level ranges nor promises for hydrogen steel.
Analysis — import-cost scenario: assume €60, €80 or €100/tCO₂ (the market was €90.16 on 5 November), direct embedded emissions E of 2.00/0.15/1.00 t/t and full-chain B of 1.364/0.066/0.475 for BF/scrap/DRI. Using the guide’s 95% 2027 factor and illustrative Table 2-3 benchmarks, correction factor 1 and no overseas carbon-price credit: cost = price × max(E − 0.95B, 0). BF working at €80: (2.00 − 0.95 × 1.364) × €80 = €56.34/t; at €100 it is €70.42/t. The CBAM certificate price will follow EU auction prices, so update the scenario with the market.
The steel guidance uses embedded direct emissions, not the worldsteel averages. An actual declaration needs the applicable CN code, origin, production year, verified inputs or prescribed defaults, precursors and carbon-price evidence; the total free-allocation adjustment cannot simply be borrowed from this panel. EU-made steel faces ETS; CBAM concerns covered imports.
Availability and the buying decision
Dunkirk remains a BF site; ArcelorMittal targets its new EAF for 2029. Arvedi Cremona already operates EAF flat-steel lines. SSAB’s 28 October report targets Q2 2027 for the Oxelösund EAF; thyssenkrupp’s Duisburg DRI plant will start on natural gas; Stegra’s 30 September update says Boden needs more completion funding. A project target is not confirmed saleable output.
Analysis — buyer: contract for an emissions limit and dated grade approval. Mill: power, feedstock and ramp-up determine what can be promised. Trader/service centre: retain heat-level evidence and agree an approved substitute if the nominated route slips. No route supplies a universal lead time in weeks.
What would change this view: verified supplier emissions, binding delivery terms or a revised commissioning date. Next action: review these conditions before 1 January 2027 and at every delivery promise; use current supplier offers, not route averages, to negotiate price. See also why hydrogen-ready can mean gas first.
Verification status: Verified
Route data, carbon price and company statements were checked against the sources listed on 4 November 2026; links, carbon price and the Infographic tag re-checked on 5 November 2026. The CBAM figures are an explicitly assumed scenario, not a supplier default or a customs declaration; relative cost is a global-average ranking, not a European offer.
Ask the Analyst
“What could CBAM add to Indian HRC delivered to Rotterdam in 2027?”: landed cost with duty, quota and CBAM in one answer.Ask the AnalystSources
Primary sources
- Sustainability Indicators Report 2025 — 2022–24 route data — World Steel Association, 2026-02
- Guidance No. 4 — CBAM free allocation adjustment, Tables 2-1 and 2-3 — European Commission, DG TAXUD, 2026-08-14
- Guidance No. 5d — iron and steel — European Commission, DG TAXUD, 2026-08-14
- EU emission allowance price, Dec-26 — oEnergetice.cz (ICE Endex data), 2026-11-04
- Weekly market data: EUA Dec-26 settlement 30 October — Advantag, 2026-11
- Decarbonizing Steel — Columbia Business School, Climate Knowledge Initiative, 2024-10
- Breakthrough Agenda Report 2025 — Steel — International Energy Agency, 2025
- ArcelorMittal Dunkerque — installations — ArcelorMittal, accessed 2026-11-04
- ArcelorMittal confirms an electric arc furnace in Dunkirk — ArcelorMittal, 2026-02
- Cremona — production site — Arvedi, accessed 2026-11-04
- Report for Q3 2026 — SSAB, 2026-10-28
- Stegra implements changes following 100-day review — Stegra, 2026-09-30
Last fact-check: 5 November 2026.