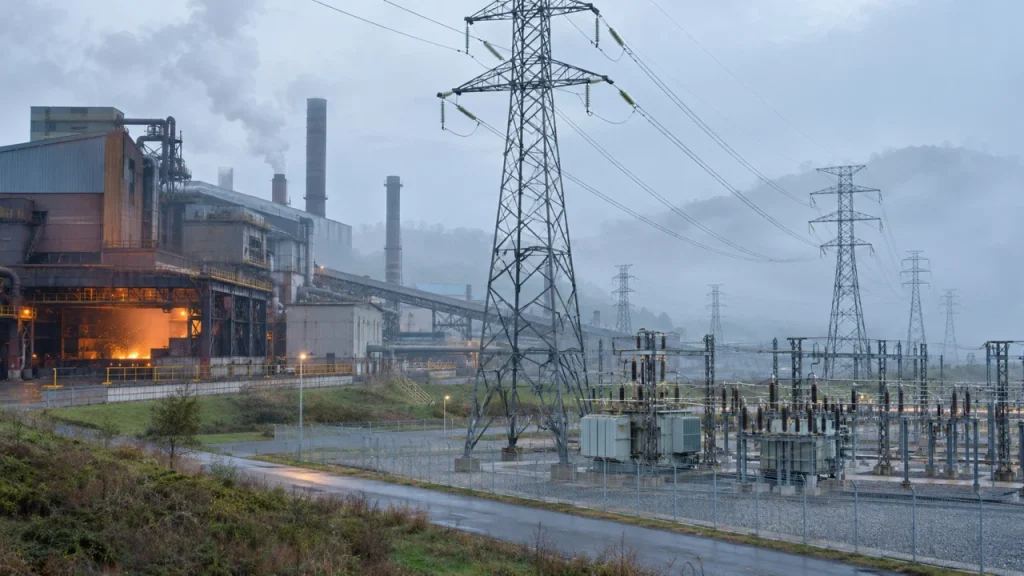
Italy’s steel association Federacciai said on 10 November that its main member steelmakers have already stopped production or are gradually stopping it, because electricity and gas costs have made running for long periods uneconomic (statement reported by Teleborsa). It did not name the companies or say how much output is affected. Italy made 20.7 Mt of crude steel in 2025, 90% of it in scrap-based electric arc furnaces, so the warning matters most to EU buyers of Italian rebar, wire rod, merchant bars and electric-arc hot-rolled coil. The step now: before you confirm November and December orders from an Italian mill, ask it to confirm the rolling date in writing and whether it will add an energy surcharge.
What Federacciai said
Federacciai said continuing production at current prices was “economically unsustainable” and put Italian mills at a serious disadvantage to European competitors, even though Italy’s steel industry is among the most decarbonised in Europe. It will ask the metalworkers’ unions Fiom, Fim and Uilm for a meeting in the coming days. Mining.com also reported that the association did not name the plants. The figure for 2025 output and the 90% electric-furnace share come from Federacciai’s April 2026 submission to the Italian parliament.
Reach steel buyers and importers worldwide
Put your brand in front of the people who buy and trade steel.
Advertise with LoharoThe same day, Italy’s wholesale power price (PUN) averaged €293.86/MWh, according to the market operator GME; in the North zone, where much of the industry sits, the day-ahead price was €310.16/MWh (Energy-Charts). Corriere della Sera reported that the government had approved a decree the day before that caps, for 18 months, the gas cost used to set power prices at €58.9/MWh, and quoted environment and energy security minister Gilberto Pichetto Fratin as expecting an average cut of about €15/MWh from January.
Is Italy really dearer than its neighbours?
Federacciai’s claim of a competitive gap was clear in October. Early November tells a different story for Germany, though not for Spain.
| Day-ahead power, €/MWh | Oct 2025 | Oct 2026 | 1–10 Nov 2026 |
|---|---|---|---|
| Italy North | 112.12 | 235.58 | 281.05 |
| Germany-Luxembourg | 84.40 | 169.27 | 274.91 |
| France | 57.47 | 165.83 | 266.31 |
| Spain | 75.75 | 166.59 | 204.08 |
| Italy North minus Germany | +27.72 | +66.31 | +6.14 |
Analysis Italian power has roughly doubled in a year. Its premium over Germany narrowed from about €66/MWh in October to about €6/MWh in the first ten days of November, as German, French and Spanish prices rose too. So the halts reflect a high absolute price rather than a gap that is still widening, and other electric-furnace mills in Germany and France face similar spot costs. That does not mean they will cut output: Federacciai’s statement covers only Italy, and other associations have not said the same. Spain remains about €77/MWh cheaper than northern Italy.
Loharo calculation: what the power price adds per tonne
Inputs: modern electric arc furnaces use about 400–500 kWh of electricity per tonne of steel (Journal of Sustainable Metallurgy); we take 450 kWh/t as a midpoint. worldsteel puts the whole scrap-based route at 2.3 GJ of electricity per tonne of crude steel (worldsteel), which is 2.3 ÷ 0.0036 = 639 kWh/t; we round to 640 as an upper case. Cost per tonne = price in €/MWh × kWh/t ÷ 1,000.
| Power price (€/MWh) | At 450 kWh/t | At 640 kWh/t |
|---|---|---|
| Italy North, Oct 2025: 112.12 | €50/t | €72/t |
| Italy North, Oct 2026: 235.58 | €106/t | €151/t |
| Italy North, 1–10 Nov 2026: 281.05 | €126/t | €180/t |
| Italy PUN, 10 Nov 2026: 293.86 | €132/t | €188/t |
| Spain, 1–10 Nov 2026: 204.08 | €92/t | €131/t |
| Change, Italy North Oct to 1–10 Nov: +45.47 | +€20/t | +€29/t |
| Minister’s expected decree effect: −15 | −€7/t | −€10/t |
Analysis The rise from October to early November adds about €20–29 per tonne at spot prices. Against Fastmarkets’ Italian hot-rolled coil index of €750.31/t ex-works on 10 November (reported by Eurometal), that is about 2.7–3.9% of the price. The decree, if it delivers the €15/MWh the minister expects, would take back only about a third of that rise, and not before January. Mills that bought power forward are less exposed now but will meet these prices when contracts roll over.
What it means for buyers
Analysis Halts at Italian mills and tight imports point the same way for long products. In the EU’s steel tariff quota, Türkiye’s rebar line (09.9884) has been exhausted since 1 October and China’s (09.9888) had about 25 t left on 11 November, according to TARIC (China line); see Loharo’s quota run-rate graphic. For flat steel, Fastmarkets reported Italian buyers dealing at €750/t ex-works against mill targets of €780/t, and one buyer expecting the gap to close by Christmas because imports are tight. That is one market view, not a forecast. Check your contracts for energy-surcharge and force majeure clauses, and keep a second supplier option for first-quarter rebar and wire rod.
Stay ahead of the steel market
What to watch
- Federacciai’s meeting with the unions: whether the association or individual mills name plants, dates or volumes.
- The decree: whether parliament keeps the €58.9/MWh gas cap and when the €15/MWh cut reaches industrial bills.
- Daily PUN and North-zone prices: a fall back towards October’s level (about €236/MWh in the North) would ease the pressure; the former Ilva sale is a separate track (Loharo on the binding bids).
Verification status: Verified
Federacciai’s statement is checked in Italian and English reports; it names no plants. Power prices were checked against GME and Energy-Charts, and quota balances in TARIC on 11 November. The decree figures and the HRC price are attributed to Corriere della Sera and Fastmarkets; the tables are Loharo calculations with their inputs shown.
Ask the Analyst
“2,000 t HRC from India into Genoa in Q1 2027 at €610/t CFR”: landed cost with duty, quota and CBAM in one answer.Ask the AnalystSources
Primary sources
- Mercato del Giorno Prima, daily report, 10 November 2026 (in Italian) — GME, 10 November 2026
- Federacciai submission to the Chamber of Deputies, 8 April 2026 (in Italian) — Federacciai, April 2026
- TARIC quota details 09.9884 (Türkiye, rebar) — European Commission, DG TAXUD, read 11 November 2026
- TARIC quota details 09.9888 (China, rebar) — European Commission, DG TAXUD, read 11 November 2026
- Raw materials — worldsteel, accessed 11 November 2026
Supporting sources
- Federacciai: costo energia insostenibile, principali aziende siderurgiche fermano produzione (in Italian) — Teleborsa, 10 November 2026
- Italian steelmakers halting production due to high energy costs, industry group says — Mining.com, 10 November 2026
- Caro energia, le acciaierie italiane fermano la produzione (in Italian) — Corriere della Sera, 10 November 2026
- Day-ahead spot prices by bidding zone — Energy-Charts, Fraunhofer ISE, read 11 November 2026
- European HRC prices firm on reduced imports, higher energy and transport costs — Eurometal (Fastmarkets), 11 November 2026
- The influence of electric-arc-furnace input feeds on its electrical energy consumption — Journal of Sustainable Metallurgy, 2021
Related on Loharo
- How fast are the EU’s new steel import quotas running out?
- Two binding bids for the former Ilva: what Arvedi’s EAF plan and Jindal’s imported-slab model mean
Last fact-check: 11 November 2026.
Planning steel imports into the EU? Estimate CBAM costs with the free calculator using EU default values. For supplier-specific emissions and a portfolio review, see the CBAM Cost Check.